
How much does your bank pay you?
Ask it honestly. Look at the statement. Those digits after the decimal point. While real inflation eats your purchasing power at a pace no official figure fully admits, your money sits parked, collecting a handout that doesn’t even tie the loss.
Today I’ll show you how to collect, on a fixed basis, up to 18%.
And the word that matters in that sentence isn’t the 18. It’s fixed.
Because we’ve all lived the mirage of the bond. They tell you it’s the safe thing. The boring thing. And then you open the chart of a TLT and you see a “risk-free” asset that collapsed by nearly half when rates rose.
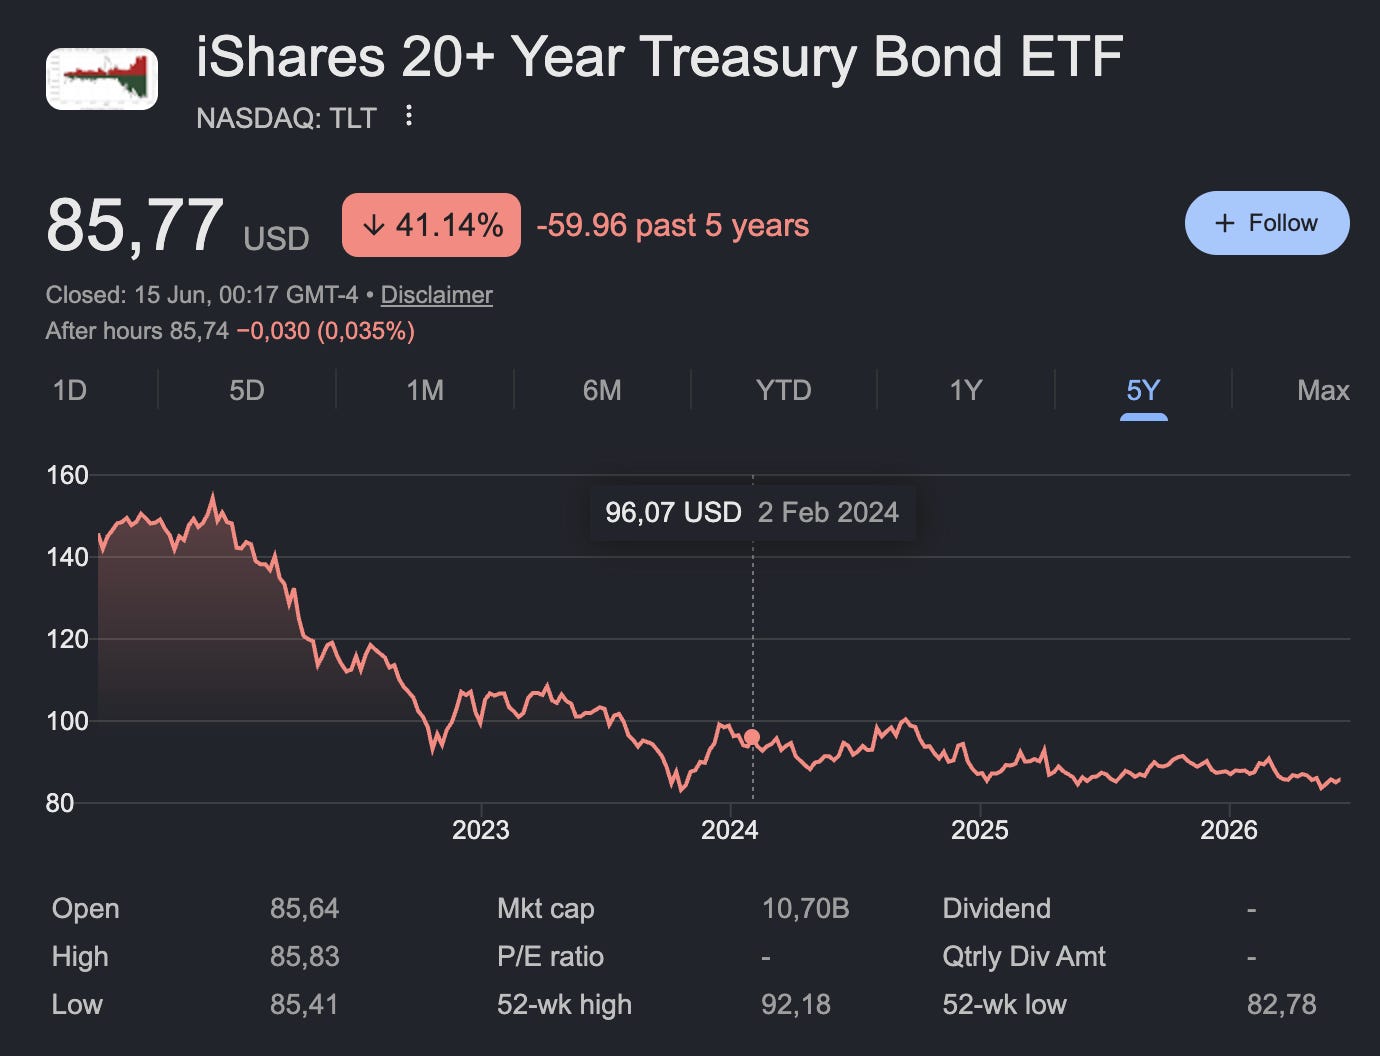
Or a SHY that barely moved but didn’t pay you anything worth remembering either. The problem with a bond bought through an ETF isn’t that it pays little. It’s that you don’t know what you’re going to collect. The market imposes the duration on you. The price fluctuates under your feet. You buy “fixed income” and end up with an asset whose value depends on what the next Federal Reserve chair decides to do.
What if you could keep the only good part of a bond, knowing exactly how much you collect and when and throw away the rest?